Home equity line of credit
Cash from your home in as fast as 5 days.
Pay off your credit cards and fix up your home. Up to $750,000. Keep your low mortgage rate. Credit from 640.
Question 1 of 9
What would you use the cash for?
Free. Won't affect your credit score. About 2 minutes.
- Free to check
- Won't affect your credit score
- No Social Security number needed
- About 2 minutes
The big numbers
- Cash from your home$100K to $750K
- Funded in as fast as5 days
- Credit from640
- Keep yourfirst mortgage

Pay off your credit cards
The bills keep coming.
The card balances keep growing.
One move can pay them off.
And keep your low mortgage rate.
Card cost calculator
What will your cards cost you?
See what your cards will cost if you keep paying them the way you do now.
Your card interest rate
Please type a rate from 1% to 40%.
What you pay each month
At this payment the balance never goes down.
Your home can do more than pay off cards.
Tap what you would use it for. Change any amount with the minus and plus buttons.
Your cash plan:$100,000
$0Up to $750,000
Still room for $650,000 more
Lines start at $100,000. Pay off your cards and still have $75,000 left over.
Free. Won't affect your credit score. About 2 minutes.
Fix up your home
The roof can't wait.
Fix it now.
Love your home again.
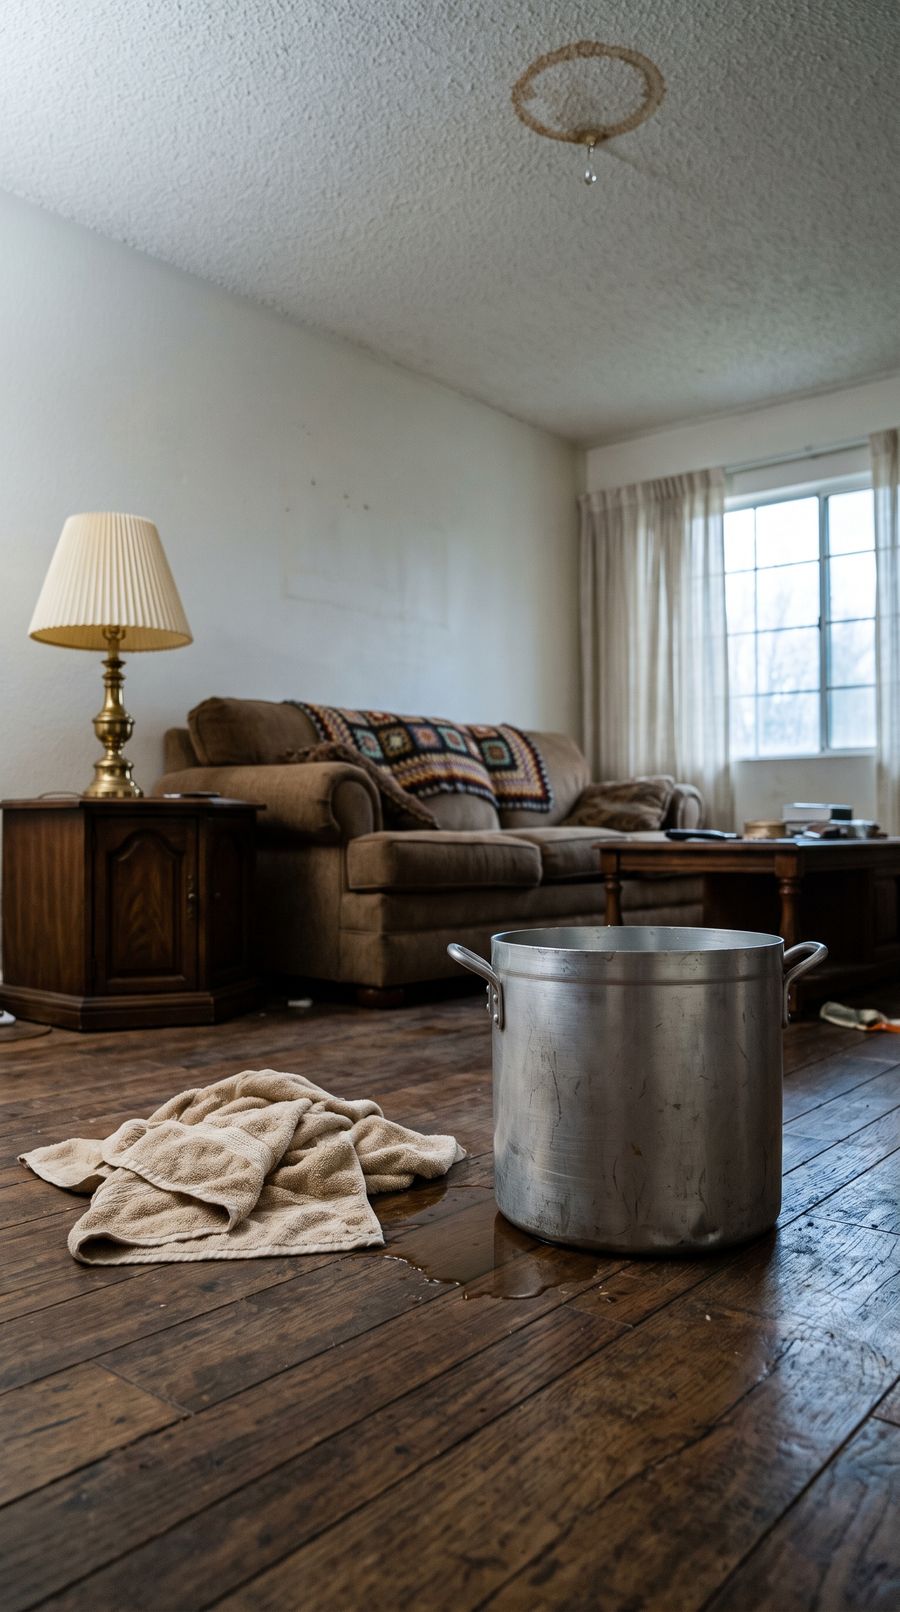
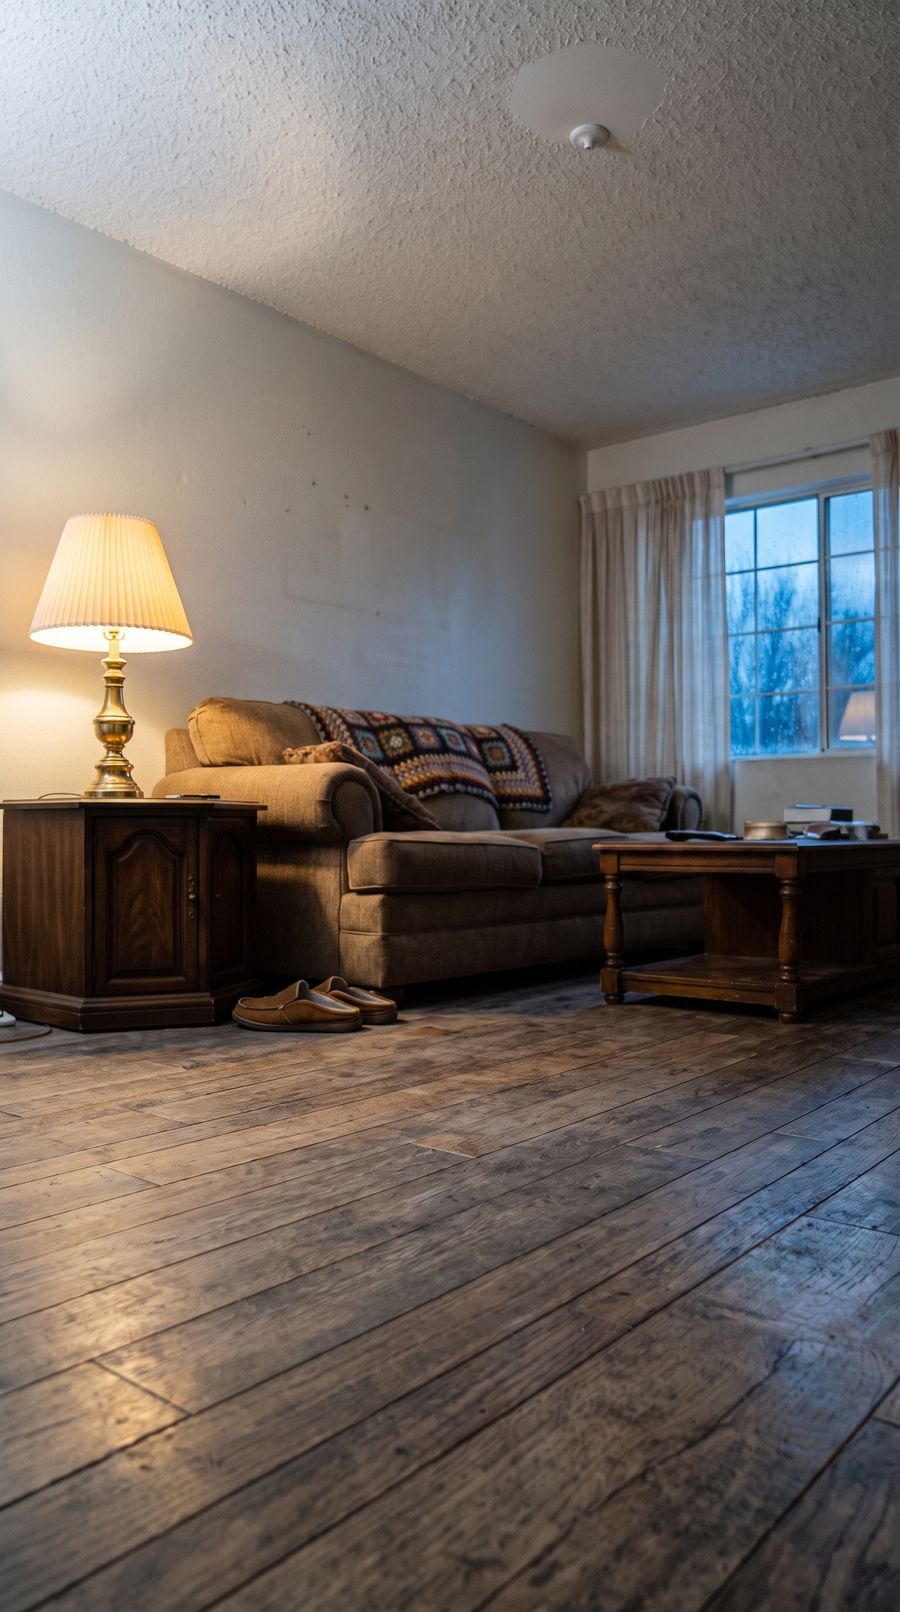
Drag to compare
From questions to cash in as fast as 5 days
Here is what the fastest week can look like.
As fast as 5 daysCash in your account
- Monday
Answer a few questions. See your estimate.
- Tuesday to Thursday
A licensed loan officer helps with the paperwork.
- Friday
Cash in your account, as fast as 5 days.
Start on Monday, and the cash can be in your account as soon as Friday.
Keep your first mortgage and its low rate
Your first mortgage does not change. Same loan, same rate, same payment. The home equity line is a separate account that sits beside it.
Your mortgage
Same loan, same rate
Home equity line
New and separate, ready when you need it
Use it like a faucet
Turn it on when you need cash. Pay it back, and the money is there to use again.
Still available$750,000
Used$0
Try it. Tap Use $100,000.
Your home has been working for you. Put it to work.
How it works
Answer a few questions
About 2 minutes. Free, and it won't affect your credit score.
See your estimate
See about how much cash your home may have for you.
A loan officer helps you finish
A licensed loan officer helps with the paperwork. You decide.
Questions people ask
Will checking affect my credit score?
No. Checking is free and won't affect your credit score. No Social Security number needed.
How much can I ask for?
Lines go from $100,000 up to $750,000. The real amount depends on your home's value, what you still owe, your credit and your income.
Will my first mortgage or low rate change?
No. Your first mortgage stays the same, with the same rate and the same payment. The line of credit is a separate loan.
Can I get one if I'm retired?
Yes, many retired homeowners use a line of credit. Lenders look at income like Social Security, pensions and retirement accounts. A loan officer can tell you what counts.
Could I lose my house?
A line of credit uses your home as security, so you need to make the payments. If you can't pay, you could lose your home, just like with a mortgage. Only borrow what you know you can pay back.
How do you make money?
Checking your options is free for you. If you choose to take a loan, the licensed brokerage is paid for setting it up, and that is explained before you sign anything. You never pay us to see your options.
See your number. It takes about 2 minutes.
Free to check. Won't affect your credit score. No Social Security number needed.
Question 2 of 9
- Your plan
- Your home
- Your options